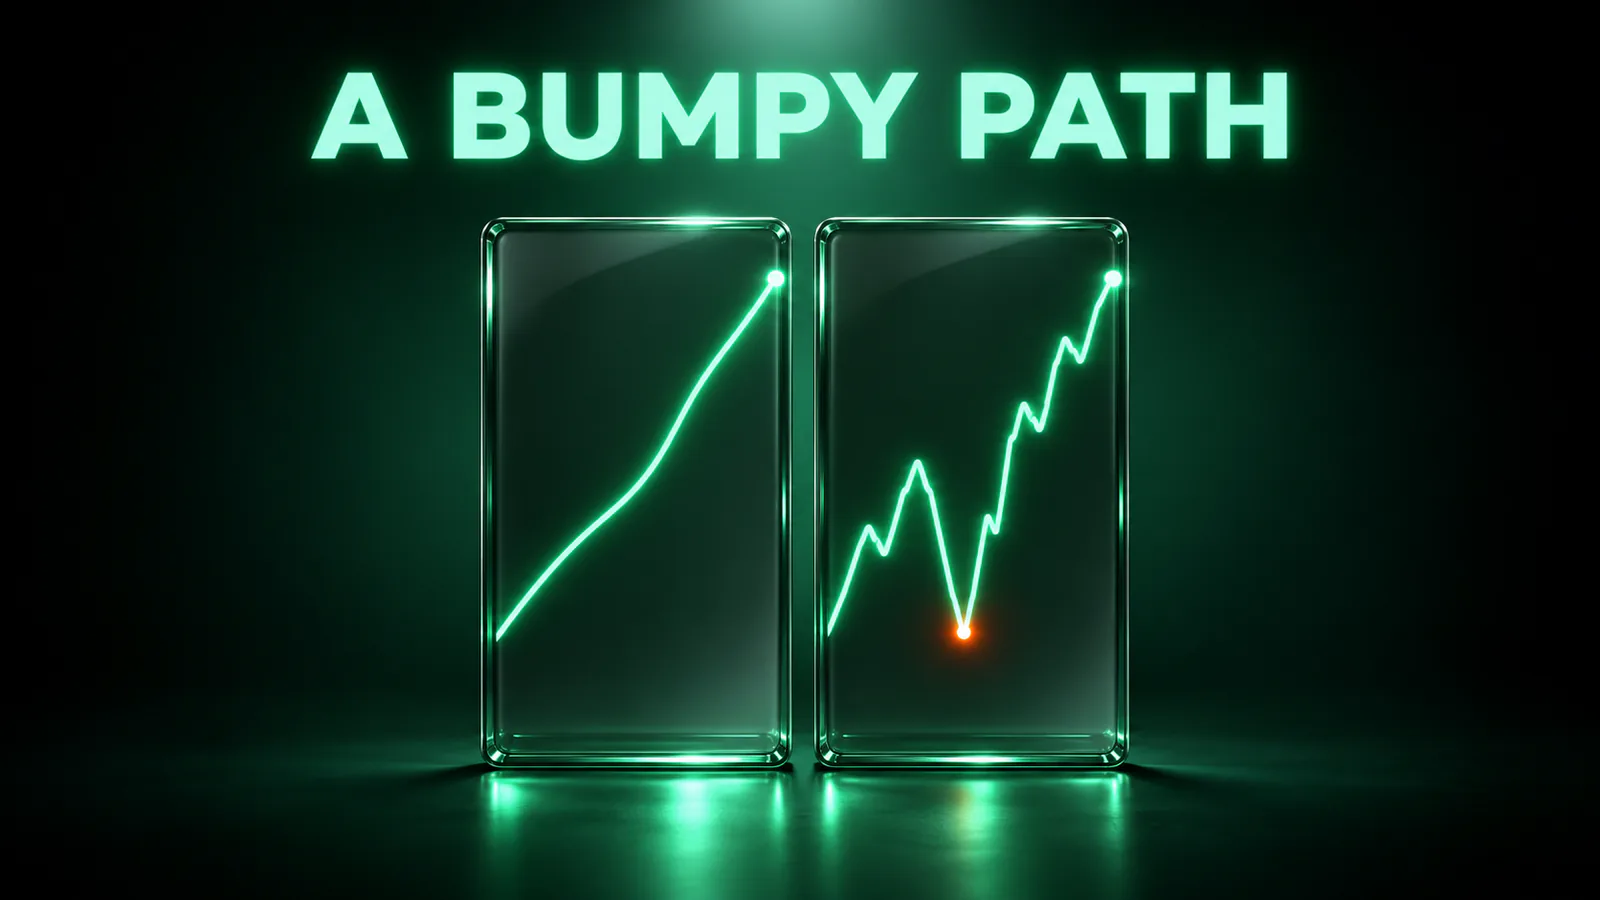
You can end a month with a profit and still have had a terrible month. One trader gets there in small, steady steps. Another gets there through a deep hole and a lucky recovery. The profit is the same. The ride is not.
The Sharpe ratio puts that difference into a single number. It takes the average return of a series, subtracts a reference rate, and divides the result by how much the returns swing around their average. The Sortino ratio does the same, except that it only counts the swings that go down.
Both numbers look precise, and both are easy to misread on a trading record of your own. This piece explains how they are calculated, what they quietly assume, and where they mislead. It stays provider-neutral, contains no market figures and gives you no target value to aim for, because there isn't one.
Key Takeaways
- The Sharpe ratio divides excess return by the total swing of returns; the Sortino ratio divides it by the downside swing alone.
- The same results can produce very different ratios, depending on the period, the reference rate, the annualization and the calculation method.
- Short records, few trades and rare large losses distort both ratios, and the number itself gives no warning.
- There is no universally good value; a ratio is only comparable with another one calculated the same way.
Risk-Adjusted Return: Why Raw Profit Is Not Enough
A raw profit figure answers one question: how much did the series make? It says nothing about what you had to sit through to get it. A risk-adjusted return adds the second half. It scores the result against the risk taken along the way.
That matters for a simple reason. A bumpy path is a fragile path. The same profit earned with large swings means your account spent more time far from its peak, closer to any loss limit, and more exposed to a run of bad periods. Two series with identical totals can carry very different odds of surviving the next month.
Risk, in these ratios, has a narrow meaning. It is not your stop distance, your leverage or your worst trade. It is the dispersion of your returns, measured as a statistic. That is a useful definition, but it is only one definition. Keep that in mind, because the blind spots further down come from exactly that narrowness.
The Sharpe Ratio Formula in Words
The calculation has three parts. Written out as a line, it reads:
Sharpe ratio = (average return − reference rate) / standard deviation of returns
The average return is the mean of your period results: daily, weekly or per trade, whatever your series is made of. The reference rate is what you could have earned without taking the risk, usually a cash-like rate. On a short trading record, it can be set to zero, which turns the numerator into your plain average return.
The standard deviation in the denominator measures how far your period results typically sit from their own average. If you want the full picture of what it captures and what it misses, our piece on volatility in crypto explains it as a measure of dispersion.
Here is the part worth remembering. The standard deviation counts a surprise to the upside exactly like a surprise to the downside. A sudden large win raises the denominator as much as a sudden large loss of the same size. In the Sharpe ratio, an unusually good period is treated as risk. Upside counts as risk.
For a fund with roughly balanced swings, that is a reasonable shortcut. For a trader whose results lean strongly in one direction, it can be a poor description of what actually happened.
The Sortino Ratio: Only the Downside Counts
The Sortino ratio keeps the numerator and changes the denominator. Instead of the standard deviation of all results, it uses the downside deviation: a measure built only from the periods that fell below a threshold you set in advance.
Sortino ratio = (average return − minimum acceptable return) / downside deviation
The threshold is called the minimum acceptable return. It can be zero, the reference rate, or any hurdle you choose. Every period above it counts as zero in the denominator. Every period below it counts by how far it fell short, squared, so larger shortfalls weigh more than small ones.
The convention matters here too. Some calculations average the squared shortfalls over all periods, others only over the periods below the threshold. Both conventions exist, and they produce different numbers from the same series. A Sortino ratio without its method is half a number. Ask for the method.
Sortino vs Sharpe is therefore not a contest between a good ratio and a bad one. They answer slightly different questions. The Sharpe ratio asks how much return you earned per unit of total swing. The Sortino ratio asks how much return you earned per unit of harmful swing. Because they divide by different measures, their values do not sit on one scale, and a gap between them on a single record says little by itself. Across records measured the same way, they can part ways.
The split is clearest when two series share the same average and the same total swing, but lean in opposite directions.
The lesson travels beyond any set of figures. When two series measured the same way share a Sharpe ratio but not a Sortino ratio, the difference is itself information. It tells you that their shortfalls weigh differently against what each series earns, and it is worth finding out where each series takes its hits and why.
Where the Number Misleads
Both ratios compress a whole series into one figure. That compression is the point, and it is also where the trouble starts. The following blind spots apply to both, unless noted.
Short records and few trades
A ratio calculated from a handful of periods is an estimate, and a noisy one. A few lucky weeks can produce a high value, and the next few weeks can cut it sharply. The uncertainty around the estimate narrows only slowly as the record gets longer, so a short record can look impressive without being reliable.
Counting trades instead of periods does not fix this. If your series is made of trades, a small number of trades gives a small sample, whatever the time span. Small samples flatter. Before you read the ratio, read the count behind it. Our trading journal guide covers how to build the record these numbers depend on.
Rare large losses
The standard deviation describes typical swings. It says little about the rare, extreme period. Rare losses hide in calm averages. A series of many small gains and an occasional large loss can show a high Sharpe ratio for a long time, right up to the period in which the loss arrives. Then it drops.
The Sortino ratio is more sensitive to losses, but only to losses that are already in the sample. If the bad period has not happened yet, neither ratio can see it. A smooth record with no deep losing period is not proof that the strategy has none.
Smoothing by the way you record results
A ratio can only be as honest as the series it is fed. If you log results only when a trade closes, the swings of open positions never enter the record. A losing position held for days and then closed near flat shows up as a quiet stretch, even though your account went through a deep valley.
Recording equity at the end of each period, open positions included, gives a rougher but truer series. The difference between the two views is the difference described in equity vs balance. A ratio built on balance alone tends to look smoother than the risk you actually carried.
Costs count too. A series measured before fees overstates the average return, and usually the ratio with it. Funding payments can be paid or received while a position is held, so leaving them out can push the series too high or too low. Score the results you actually kept.
Annualization and the period you choose
Ratios are usually quoted on an annual basis so that different series can be compared. The textbook shortcut multiplies a per-period ratio by the square root of the number of periods in a year. That shortcut assumes that each period is independent of the last. Check that assumption.
When good periods tend to follow good periods, and bad follow bad, that assumption breaks. The shortcut then understates the true annual swing and overstates the annual ratio.
Crypto perpetuals add a second question. A market that trades around the clock has no closing bell, so the number of periods in a year is a choice, not a fact. State your choice. Calendar days and weekdays give different annual figures from identical results.
What Is a Good Sharpe Ratio? Why There Is No Universal Answer
This is the question that usually comes next, and the honest answer is that a single good value does not exist. Any threshold you read somewhere silently assumes a period length, an annualization, a reference rate, a cost treatment and a record length. Change any of those and the same results produce a different number. Thresholds travel badly.
That does not make the ratio useless. It changes how you use it. Compare like with like, or not at all. A Sharpe ratio is most informative when you set it against another one built the same way: your own series last quarter against this quarter, or one version of a strategy against another on the same data and the same method.
A ratio from a backtest and a ratio from live trading are also two different things. The backtest tends to omit slippage, missed fills and the decisions you would have made differently under pressure. Read the live figure as the one that describes you. What a backtest can show, and why its result describes the past rather than forecasting the future, is set out in our guide to backtesting.
Three Other Ways to Score a Series
Sharpe and Sortino are two measures among several for scoring a record. Three more are worth knowing, and each has its own blind spot.
Profit Factor
The profit factor divides the sum of all winning trades by the absolute sum of all losing trades. It is quick to calculate from a trade list, and the trading journal analyzer shows it alongside win rate, expectancy and drawdown.
Its weakness is that it ignores order and timing. Sequence matters. The same set of trades scores the same whether the losses came spread out or all in a row. A few large trades can dominate it, and with no losing trades in the record, there is nothing to divide by. It also does not tell you how a single win compares with a single loss; that per-trade view is covered in risk-reward ratio explained.
Calmar Ratio
The Calmar ratio divides an annualized return by the maximum drawdown over the same window. It swaps the statistical idea of swing for the most painful thing a trader actually lives through: the deepest fall from a peak. If you want that measure explained in full, see what a drawdown is.
Its weakness is that it hangs on a single point. One bad stretch decides the denominator, and nothing else in the series counts. The maximum drawdown also tends to deepen the longer you observe a series, simply because a longer window gives a deep fall more chances to happen. Calmar ratios over windows of different length are not comparable.
The Equity Curve
The equity curve is not a ratio at all. It is the running value of the account, period by period. It shows what the ratios compress away: the order of results, losing streaks, flat stretches and the moments the account sat far below its high.
Its weakness is that it is read by eye, and eyes are easy to steer. The start date, the time span and the scale of the vertical axis all change the impression the same curve gives. Axes can flatter. Use it to understand a ratio, not to replace one.
| Measure | What it scores | Blind spot |
|---|---|---|
| Sharpe ratio | Excess return per unit of total swing | Treats large gains as risk |
| Sortino ratio | Excess return per unit of downside swing | Blind to losses not yet in the sample |
| Profit factor | Gross wins against gross losses | Ignores order and timing |
| Calmar ratio | Annual return against the deepest fall | Hangs on a single low point |
Reading Ratios Next to Drawdown and Risk of Ruin
Each of these measures answers a different question. Sharpe and Sortino ask how much return you earned per unit of swing. Drawdown asks how far the account fell from its peak. Risk of ruin asks how likely it is that a losing streak reaches a loss limit before the plan works out. None of them answers the others' questions. Different questions, different tools.
That is why a high ratio is not reassurance on its own. A series can score well and still have come close to a loss limit, because the ratio measures the shape of the returns, not the distance between your equity and a boundary. On any account with a loss limit, that distance is what decides whether the series continues at all.
If you want to look at that second question directly, the risk of ruin calculator simulates how likely a losing streak reaches a loss limit before a profit target. The ratios in this article describe a record after the fact; the simulation looks at the odds going forward.
All of these numbers share one limit. They describe the past. A ratio is a summary of what a series did, under a given method, over a given window. It is not a forecast, and it is not a promise about the next period. For the order in which these risk topics build on each other, the learning paths on our learn page set them out step by step.
Conclusion
The useful habit is to treat a Sharpe or Sortino figure as a question, not a verdict. A high number asks you to check the method, the length of the record and whether your losses are already in the sample. A low number asks whether your large swings were gains or losses.
That leaves you with a real trade-off. You can quote one tidy figure and accept that it hides how it was made. Or you can report the ratio together with its period, its method and a drawdown figure, and give up the comfort of a single number. The second way is less impressive. It is also the one you can still trust after a bad month.
FAQ
Should I use the Sharpe ratio or the Sortino ratio?
Use both, but compare like with like. The two divide by different measures, so even evenly spread results can show a clear gap between them, and on a single record that gap alone does not tell you which way your results lean. Two records measured the same way that share a Sharpe ratio but not a Sortino ratio do tell you something: their shortfalls weigh differently against what each one earns. The Sortino ratio is the more fitting description when large gains are part of your approach, but only if your record already contains losing periods.
Can I calculate a Sortino ratio when I have no losing periods?
Not meaningfully. With no period below the threshold, the downside deviation is zero and the ratio has nothing to divide by. Mathematically, the result is undefined. That does not mean the series carries no risk. It means the sample has not yet shown its downside, which is a reason to wait for a longer record.
Does leverage change my Sharpe ratio?
In a simple model, no. Scaling every position up by the same factor scales the average return and the swing by that factor too, so their ratio stays the same. In practice, liquidation levels break that symmetry. Leverage leaves the ratio roughly intact while making each drawdown deeper and a loss limit closer.
What does a negative Sharpe ratio tell me?
That the series earned less than the reference rate. Be careful when ranking negative values, though. With a negative numerator, a larger swing makes the ratio less negative, so a more erratic losing series can look better than a steadier one. Below zero, read the average return and the drawdown instead of the ratio.
Should I calculate the ratio per trade or per period?
Either works if you stay consistent. A per-trade series ignores how long each trade was open and the flat time between trades. A per-period series includes quiet days and open-position swings. The two produce different numbers from the same account, so state which one you used and never compare one against the other.